Inheritance Tax Documents UK: What to Gather (Will, Trusts, Gifts, Property
Gather your will, trust deeds, gift records and property papers now. This UK checklist shows which inheritance tax documents your executors will need.
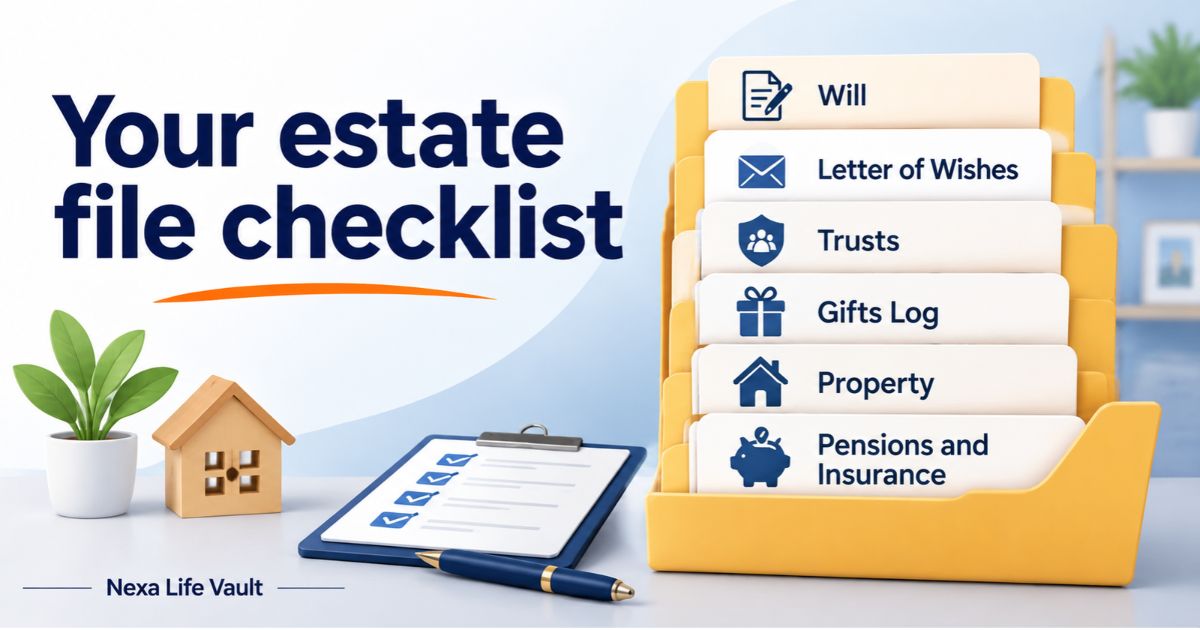
For inheritance tax in the UK, gather your will, any trust deeds, records of gifts you have made, and proof of what you own and owe. That means property papers, bank and investment statements, pension details and life insurance policies. Your executors use these to complete HMRC forms. Thresholds change, so check GOV.UK.
This is general information, not legal, tax or financial advice.
Most families only start hunting for inheritance tax documents UK rules require after someone has died. By then the paperwork is scattered across drawers, email inboxes and old online accounts. Executors have deadlines, and HMRC will ask for evidence. This article lists what to collect now, explains why each item matters, and shows how to keep it all in one place your executors can find.
What is inheritance tax, and who deals with the paperwork?
Inheritance tax (IHT) is a tax on the estate of someone who has died. Your estate means everything you own, minus what you owe: property, savings, investments, vehicles, possessions and, from April 2027, most unused pension pots too.
Not every estate pays. Whether yours does depends on its total value, who inherits, and the allowances in force when you die. Even when no tax is due, executors often still need to report the estate to HMRC, so the paperwork matters either way.
The people who deal with it are your executors (if you leave a will) or administrators (if you do not). They gather the facts, value everything, fill in the forms and pay any tax before they can distribute the estate.
Verify with the official source before acting: GOV.UK's inheritance tax pages and HMRC guidance set out current thresholds, rates and reporting rules. Rates and allowances can change from one tax year to the next.
What inheritance tax documents UK executors need: the checklist
Use this table as your starting point. You do not need everything on day one. Start with the top rows and work down.
| Document | Why it matters | Where to find it |
|---|---|---|
| Signed will and any codicils | Shows who inherits and who the executors are | Solicitor, home safe, will-storage service |
| Letter of wishes | Guides executors and trustees on your intentions | Kept with the will, or with your solicitor |
| Trust deeds and trustee records | Shows what sits inside or outside your estate | Solicitor, trustees, financial adviser |
| Gift records | Shows what you gave away, when, and to whom | Bank statements, your own notes, emails |
| Property papers | Proves ownership and helps set a value | Title deeds, Land Registry, mortgage lender |
| Bank, savings and investment statements | Fixes the value of liquid assets | Online banking, brokers, annual statements |
| Pension and life insurance documents | Shows what may count in the estate and who is named | Providers, annual pension statements |
| Debts, loans and funeral costs | Reduces the value of the estate | Lenders, credit card statements, invoices |
| Marriage or civil partnership certificate, and a late spouse's estate papers | May allow unused allowances to pass to the survivor | Certificate drawer, previous executors, solicitor |
Your will and any codicils
The will is the anchor document. It names your executors, says who gets what, and may include trusts. A codicil is a signed change to a will, so collect every codicil with the original.
Executors need the original signed will to apply for probate. A photocopy will not do. If you are unsure where yours is, read our guide on how to store a will safely.
Your letter of wishes
A letter of wishes is a short, informal note that explains how you would like things handled. Typical examples: who should get a family heirloom, how a trust should be used for grandchildren, or how you want your funeral run.
In England and Wales a letter of wishes is generally not legally binding. Executors and trustees usually treat it as guidance. Write it separately from the will, date it, sign it, and update it when your life changes. Scottish and Northern Irish rules can differ, so ask a solicitor in the relevant nation.
Trust documents
If you have set up a trust, or you benefit from one, keep the trust deed, any letters between you and the trustees, and the trustees' contact details. Also keep records of what was put into the trust and when.
Trusts are treated differently from assets you own outright, and HMRC has its own reporting rules for them. The documents show executors what is inside your estate and what is not, so they do not guess.
Records of gifts
This is the area where families most often get stuck. Gifts you make during your lifetime can still matter for inheritance tax, especially if you die within seven years of making them. HMRC asks executors about gifts made in the years before death.
Good gifts records for IHT include:
- The date of each gift
- The amount or a description of the item
- Who received it
- The bank statement showing the transfer, or a receipt
- A note of why you gave it, if an exemption might apply (for example, a wedding gift or regular gifts from spare income)
A short example: Margaret gave her daughter money towards a house deposit and, in later years, paid her grandchildren's school trip costs. When Margaret died, her son, the executor, had only a vague memory of the deposit and no record of the smaller gifts. He spent weeks piecing it together from old bank statements. A one-page gifts log kept in the same folder as her will would have saved most of that.
Verify with the official source before acting: GOV.UK explains which gifts are exempt, which are taxable, and how the seven-year rule works. Do not rely on a summary here for amounts or time limits.
Property documents
For a home or other land, gather the title deeds or Land Registry title number, the latest mortgage statement, the buildings insurance schedule, and any recent valuation. If you own property jointly, note how it is held, because that affects how it passes on death.
If you plan to leave your home to children or grandchildren, keep proof of who lives there and who inherits it. Some allowances depend on a home being passed to direct descendants, and executors need to show that clearly.
Money, investments, pensions and insurance
List each account with the provider's name, the account type and the latest balance. Include current accounts, ISAs, shares, premium bonds and any foreign accounts. Add pension statements and the policy documents for any life insurance.
Pensions deserve special care. The government has announced that most unused pension funds and death benefits will be included in estates for inheritance tax from 6 April 2027. Check the latest GOV.UK guidance and ask your pension provider how this applies to you.
Debts and liabilities
Debts reduce the value of the estate, so executors need proof of them. Keep mortgage statements, loan agreements, credit card balances and any money you owe to family members. Note any promises to repay, because informal debts are hard to prove later.
What is on a practical IHT planning checklist?
Gathering paper is only part of it. Use this IHT planning checklist as a working order:
- Check your will is current. Review it after marriage, divorce, a new child, a house move or a big change in wealth.
- Name executors and tell them. They cannot find what they do not know exists.
- List everything you own and owe. One page is enough to start.
- Write down your gifts. Add new ones as you make them, with dates and amounts.
- Collect trust paperwork. Keep deeds and trustee details together.
- Find your property papers. Title deeds, mortgage details and valuations.
- Add pension and life insurance details. Note who is named as beneficiary and check it is still right.
- Write a letter of wishes. Keep it dated and signed, stored with the will.
- Pick one place for it all. A folder, a safe or a secure digital vault. Tell your executors where it is.
- Review once a year. A yearly check takes less time than rebuilding a lost record.
Common mistake: keeping the will in one place, the gift records in another, and the pension details in an email account only you can open. Executors then lose weeks tracking things down while deadlines run. Keep a single index of where everything lives, even if the originals stay in different places.
Which HMRC forms and papers will executors use?
You do not fill these in yourself while you are alive, but knowing they exist explains why the documents above matter.
- Form IHT400 (the main inheritance tax account): executors use this to report the estate's value and calculate any tax. Extra pages cover gifts, trusts, jointly owned assets and property.
- Gifts and transfers pages: these ask about gifts made before death, which is why your gifts log matters.
- Transfer of unused allowances: if a spouse or civil partner died earlier, their unused allowances may pass to the survivor. Executors need the first estate's papers to claim this.
Which forms apply depends on the estate. Some smaller estates follow a simpler process. Verify with the official source before acting: GOV.UK lists the current forms, who needs them, and the filing and payment deadlines.
How long should you keep these records?
Keep your will, trust deeds and property papers for as long as they are valid. For gift records, keep them at least until seven years after the gift, and longer is safer, because the seven-year rule counts from the date of the gift. If a gift is made into a trust, ask a solicitor how long to keep the records.
After a death, executors should keep estate records for a sensible period in case HMRC asks questions. If in doubt, ask your solicitor or check GOV.UK.
How Nexa Life Vault helps
Your estate papers belong with the Legal Vault. You can store your will details, trust deeds, letter of wishes and a gifts log in one place, kept apart from everyday documents. Keep the original signed will in a safe place too, as executors usually need the original.
The feature that matters most here is Nominee & Executor Access. You choose who can reach your estate file, so your executors are not left guessing where to look or how to start. Files are protected with AES-256-GCM encryption, with a separate key for each file.
For the money side, the Finance Vault is a natural home for bank, investment and pension statements. Nexa Life Vault does not give tax or legal advice, and a digital copy may not replace an original document.
Conclusion
Inheritance tax documents UK executors need are mostly ordinary papers: a will, trust deeds, gift records, property details and statements. The hard part is finding them quickly when it matters. Gather them once, keep a short index, and review it each year. Ready to start? Organise your estate file in Nexa Life Vault today.
This is general information, not legal, tax or financial advice. Thresholds and rules change, so check GOV.UK and speak to a qualified adviser about your own situation.
Frequently Asked Questions
Pratyush Kumar
Technology Lead & Digital Transformation Strategist
Technology leader and digital transformation strategist writing about secure enterprise data architecture, privacy-first engineering, and next-generation vault solutions.
Share this post
Comments (0)
No comments yet. Be the first to comment!